Overview of the E-Commerce Market landscape and industry significance
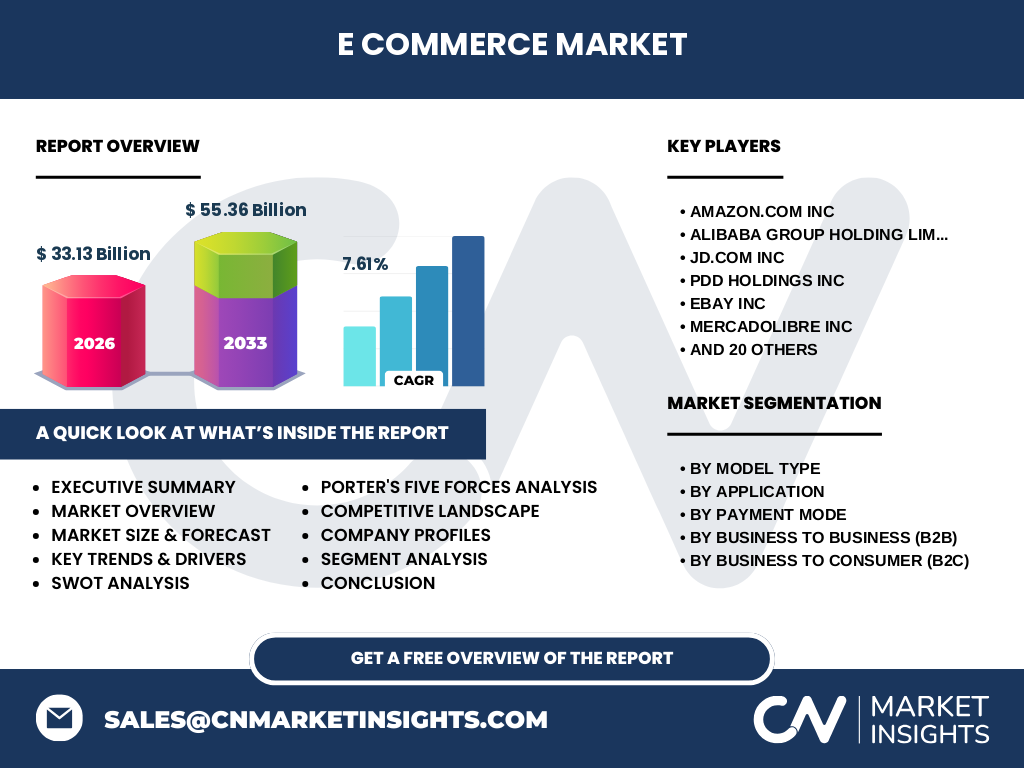
The E-Commerce Market represents a fundamental shift in global trade, encompassing digital transactions across B2B and B2C frameworks. Valued at 33.13 Billion in 2026, this sector facilitates the exchange of goods ranging from groceries to high-end electronics. Its significance lies in collapsing traditional supply chain barriers, allowing participants like Amazon.com Inc and Alibaba Group to bridge the gap between global manufacturers and end-users, thereby redefining retail distribution.
Structural growth drivers, restraints, and strategic opportunities
Primary growth is fueled by digital wallet penetration and hyper-personalized procurement services. Conversely, market expansion faces logistical bottlenecks at major ports and stringent regulatory oversight from bodies like the FTC. However, opportunities abound in sustainable logistics. Our analysis shows that firms optimizing their supplier-distributor platforms are best positioned to capitalize on the shift from physical to virtual storefronts, particularly in emerging markets with rising disposable income.
Emerging trends shaping current E-Commerce Market growth patterns
The shift toward Direct-To-Consumer (DTC) brands is accelerating as manufacturers bypass traditional retail intermediaries. We observe a technological pivot toward AI-driven inventory management, which optimizes wholesale marketplaces. Companies like Zalando SE and Wayfair Inc are successfully utilizing predictive analytics to streamline clothing and home appliance turnover, proving that data-centric operational models are now essential for maintaining market relevance in a high-velocity environment.
Impact of COVID-19 and the post-pandemic recovery trajectory
The pandemic acted as a catalyst for rapid digitization, forcing legacy retailers to adopt online retail stores overnight. Post-2020, the recovery trajectory shifted from mere survival to omnichannel optimization. While initial surges in grocery and baby goods spending have normalized, the structural change in consumer behavior is permanent, leaving companies like Walmart Inc and Coupang Inc well-integrated into a new, resilient, digitally-led supply chain reality.
Competitive benchmarking and strategic dynamics of major players
The competitive landscape is defined by intense concentration among giants like PDD Holdings Inc and JD.com Inc. Strategic dynamics center on ecosystem lock-in, where companies leverage digital wallets and B2B subscription services to create high switching costs. Our research identifies a bifurcation: while global players focus on scale, regional leaders like MercadoLibre Inc differentiate through localized logistical expertise and specialized payment mode integration, effectively insulating themselves from broader global volatility.
Executive summary of E-Commerce Market findings
Our research identifies the E-Commerce Market as a robust growth engine, projected to reach 55.36 Billion by 2033 at a CAGR of 7.61%. Key findings highlight the dominance of B2C marketplaces and the untapped potential of B2B procurement services. Companies that integrate agile payment modes—specifically digital wallets—while navigating complex regional regulatory constraints, will capture significant market share throughout the forecast period.
Projected growth forecast from 2027 to 2033
From 2027 through 2033, the market is poised for steady appreciation, climbing to 55.36 Billion. This trajectory is supported by a 7.61% CAGR. Growth will be led by the proliferation of online service platforms and the maturation of the wholesale marketplace segment, as industrial buyers increasingly demand the same friction-less purchasing experience previously exclusive to individual retail consumers.
Segmentation analysis by model, application, and payment
The market is segmented into B2B (wholesale and procurement) and B2C (retail and DTC). Applications are diverse, spanning groceries, cosmetics, and home appliances. Payment infrastructure is critical, with digital wallets and bank transfers becoming the standard, displacing traditional cash payments. This segmentation allows for targeted investment; for instance, B2B subscription services demonstrate higher recurring revenue potential compared to seasonal clothing and footwear retail cycles.
Regional market analysis and geographic distribution performance
Geographic performance shows a concentration in regions with high digital infrastructure maturity. North America and Asia-Pacific lead, driven by companies like Amazon.com Inc and Sea Limited, respectively. Regional growth is tied to local regulatory frameworks and logistical capacity. Our analysis suggests that secondary markets, particularly in developing economies, are seeing the fastest adoption rates for mobile-first payment modes, effectively leapfrogging legacy financial infrastructure common in Western markets.
In-depth review of key regional market dynamics
In North America, the market is highly competitive with a focus on logistical speed and online retail stores. In contrast, the Asia-Pacific region, spearheaded by Suning.com Group and Vipshop Holdings Ltd, focuses on integrated super-apps. These regional differences underscore why a one-size-fits-all strategy fails; local players must account for unique tax compliance and cross-border trade regulations to succeed in disparate geopolitical landscapes.
Strategic positioning of leading companies
Leading players employ distinct strategies: eBay Inc focuses on marketplace liquidity, while Chewy Inc and Lenskart dominate through vertical integration in niche categories. Meanwhile, Farfetch Limited targets the luxury segment, leveraging global logistics to bridge boutique access. These diverse positionings illustrate that the most successful firms are those that align their core technology with the specific purchase behaviors of their target demographic.
Porter's Five Forces analysis for the E-Commerce sector
The threat of new entrants is high, yet mitigated by the immense capital required for logistical infrastructure. Buyer power is amplified by transparent price comparison engines, while supplier power varies by sector, being highest in specialized cosmetics and baby goods. Competitive rivalry remains fierce among giants like Rakuten Group Inc and ASOS plc, keeping margins thin and innovation in payment modes constant.
SWOT analysis of the global E-Commerce Market
Strengths: Massive scalability and 24/7 accessibility. Weaknesses: High dependence on third-party logistics and data privacy risks. Opportunities: Expansion into B2B procurement and emerging market penetration. Threats: Increasing cross-border regulatory barriers and cybersecurity threats. Our research indicates that firms diversifying their supply chain reliance are best positioned to neutralize these threats while leveraging the inherent strength of their digital-first business models.
Value chain analysis from raw materials to end-users
The value chain originates with raw material procurement, moving through manufacturing, wholesale marketplaces, and final delivery via last-mile logistics providers. Strategic value is added at the digital interface stage, where companies like Target Corporation optimize the journey. Successful market participants control this flow by integrating supplier-distributor platforms directly with inventory management, reducing the 'bullwhip effect' often seen in traditional retail supply chains.
Investment insights and high-potential growth areas
Investors should target B2B subscription services and AI-powered procurement platforms, as these offer predictable, high-margin revenue streams. Additionally, specialized marketplaces—specifically those focusing on groceries and home appliances—present significant acquisition value. We advise caution regarding firms overly reliant on legacy cash payments, as the market is clearly pivoting toward secure, digital wallet ecosystems that offer better data collection and transaction transparency.
Conclusion and key takeaways for stakeholders
The E-Commerce Market is a high-growth sector set to hit 55.36 Billion by 2033. The primary takeaway for stakeholders is that operational agility—specifically in logistics and payment technology—is the single greatest predictor of long-term success. Firms that successfully bridge the B2B and B2C divide while maintaining compliance with evolving regional trade regulations will dictate the future of global retail.
Research methodology and data triangulation processes
Our estimates are triangulated using trade registry data, primary stakeholder interviews with sector executives, and secondary macroeconomic indicators. We cross-reference company annual reports with historical transaction volumes from major regional players. This rigorous methodology ensures that our 7.61% CAGR estimate accounts for both localized market fluctuations and broader, long-term digital transformation trends inherent in the global E-Commerce ecosystem.
Scope of the report, parameters, and limitations
This report covers global E-commerce trends from 2027 to 2033, including B2B and B2C models and major payment modes. The analysis excludes purely offline retail brick-and-mortar operations unless integrated into an e-commerce ecosystem. While the data is robust, market participants should be aware that unforeseen regulatory shifts or geopolitical disruptions in major shipping lanes may necessitate adjustments to projected growth forecasts.
Recent developments, company announcements, and strategic moves
Recent activity highlights a focus on operational efficiency. Notable moves include major partnerships between retail giants and fintech firms to enhance digital wallet checkout experiences. Companies are also investing heavily in automated warehousing to combat rising labor costs. These announcements reflect a collective industry pivot toward resilience and automation, as firms like Carvana Co and Best Buy Co Inc refine their strategies for a post-2026 growth environment.